GS 2: PolityPrelimsGS 2: Indian Constitutional Evolution, Features, Amendments, Basic Structure DoctrineGS 2: Structure and Functioning of Executive and JudiciaryGS 2: Union State Relations and Federal Structure
Cess levied on sales tax falls within State’s ambit, says SC, Pg10
Supreme Court upholds states' power to levy cess on sales tax, affirming legislative competence under Entry 54 of List II, settling decades-old dispute.
Practice MCQs
833 Students attempted
Key Highlights:
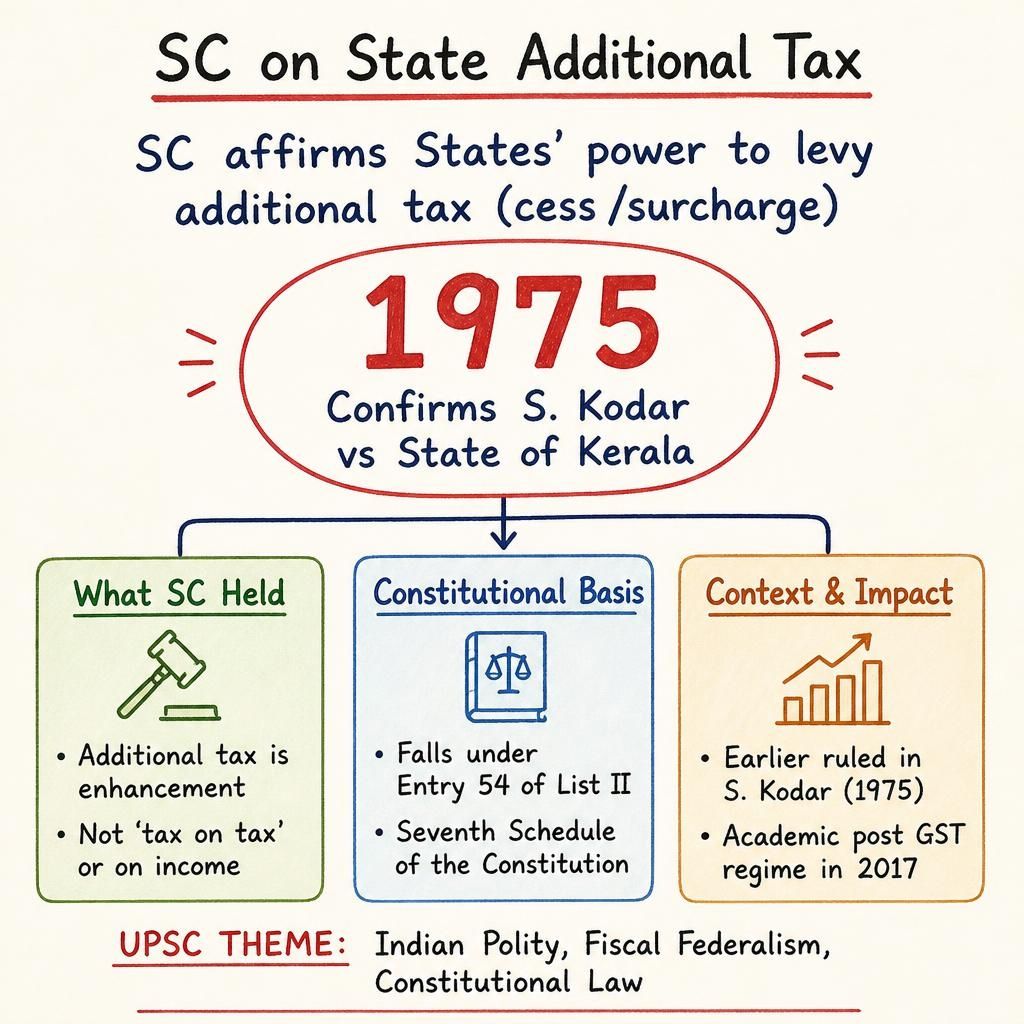
- The Supreme Court affirmed the competence of State legislatures to levy additional tax (cess/surcharge) on the sale or purchase of goods.
- This additional tax, computed as a percentage of existing sales tax, is considered an enhancement of the sales tax rate.
- The ruling confirms the 1975 judgment in S. Kodar versus State of Kerala.
- Such levies fall under Entry 54 of List II of the Seventh Schedule of the Constitution.
- The Court rejected arguments that such a levy constitutes a "tax on tax" or a tax on income.
State Additional Tax.jpg
Detailed Insights:
- A seven-judge Bench of the Supreme Court delivered the judgment, based on petitions filed as early as 1994.
- The assessees contended that a tax measured by the quantum of tax already payable does not fall upon the 'sale' or 'purchase of goods'.
- They argued that such an additional tax was a charge on the dealer's 'income' or 'fiscal burden', placing it outside the State's legislative domain.
- States maintained that the surcharge was merely an enhancement of the sales tax rate for certain dealers, with its computation method not altering its core character.
- The S. Kodar case (1975) had previously upheld similar additional sales taxes, ruling they were not taxes on dealer income but an enhancement of sales tax.
- The issue has largely become academic following the implementation of the Goods and Services Tax (GST) regime in 2017, which subsumed most sales taxes.
- The ruling reinforces the fiscal autonomy of states within their constitutionally defined taxation powers.
Key Concepts Involved:
- Entry 54 of List II: Grants State legislatures the power to levy taxes on the sale or purchase of goods other than newspapers.
- Seventh Schedule: Divides legislative powers between the Union and State governments into three lists: Union List, State List, and Concurrent List.
- Cess: A tax on tax levied by the government for a specific purpose, which must be used only for that purpose.
- Surcharge: An additional charge on tax, usually levied on higher income groups, and its proceeds can be used for any government purpose.
SuperKalam is your personal mentor for UPSC preparation, guiding you at every step of the exam journey.
Download the App


STUDY RESOURCES
CONTACT US
ⓒ Snapstack Technologies Private Limited